America’s penny persists mostly out of habit; the evidence now shows that habit is costly for taxpayers and operationally awkward for a cash economy that long ago digitized most precise-cent accounting.
At a Glance
- The U.S. Mint lost money on every cent struck in FY2024; over 3 billion pennies produced generated an estimated $85 million aggregate loss.
- Pending legislation would suspend new penny production while keeping existing pennies legal tender and preserving exact-cent pricing for electronic payments.
- Cash transactions would round only when exact change isn’t available, typically to the nearest five cents under symmetrical rules.
- The strongest counterargument is a possible “rounding tax,” with credible estimates placing the net consumer cost in the low millions annually, concentrated among cash users.
Why the penny is economically upside down
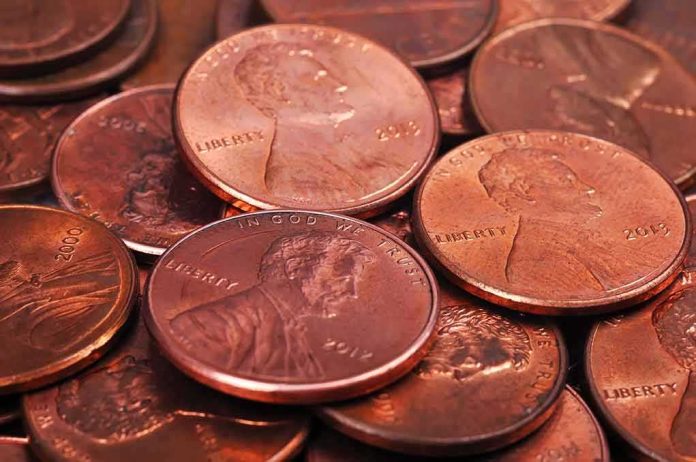
The core economic fact driving reform is seigniorage turned negative: the Mint’s unit cost to manufacture a cent exceeded its face value in FY2024. Contemporary analyses of the Mint’s 2024 reporting place the per-coin cost near 3.7 cents—more than triple its value—so every new penny is produced at a loss. Scale that by the year’s output—more than 3 billion pennies—and the arithmetic becomes policy-relevant: an estimated $85.3 million net loss tied to one denomination in one year. That is not a rounding error in a bureau’s ledger; it is a structural mismatch between materials, labor, and distribution costs and a coin whose purchasing power has withered under decades of inflation.
None of this means the cent is useless in accounting terms; it means the physical token is a poor vehicle for representing it. In a world where electronic settlement captures exact cents effortlessly, the penny’s practical role has collapsed to the narrow slice of transactions that are cash, require change, and cannot be conveniently handled with higher denominations.
What Congress’s “Common Cents” framework actually does
Legislative drafts now circulating in Congress take a conservative approach: suspend new penny production rather than demonetize the coin. Congressional Research Service materials summarizing H.R. 3074 and a Senate companion describe a design that keeps existing pennies as legal tender, authorizes limited numismatic issues, and sets a rounding policy for cash when exact change is unavailable. Electronic payments—debit, credit, ACH, instant—continue to settle to the penny exactly.
That architecture matters for two reasons. First, it addresses the government’s direct, well-quantified loss by halting the most expensive activity—minting more cents—without forcing a sudden purge of billions already in drawers and tills. Second, it aligns U.S. practice with international precedents: prices remain priced to the cent, electronic settlement is exact, and only cash totals are rounded, ideally using symmetrical rules at the transaction total rather than per-item.
Mechanics of cash rounding: how it works when designed well
Rounding is often the lightning rod in this debate, but it is also straightforward. Symmetrical rounding to the nearest five cents applies only to the final cash total after tax, not to individual prices. Under symmetric rules, totals ending in 1, 2, 6, or 7 cents round down; 3, 4, 8, or 9 round up; 0 or 5 stay put. This is the playbook many jurisdictions adopted when retiring low-denomination coins, in part because it minimizes systematic bias and reduces incentives for tactical price endings. The House-focused reporting on the Common Cents framework indicates the same logic: no change to exact-cent electronic payments, cash rounding only when exact change is unavailable, and pennies in circulation remain spendable.
Operationally, retailers implement this at the point of sale with simple logic coded into register software and posted placards describing the rule. Banks and armored carriers adjust coin orders and routes, typically with efficiency gains once low-value bulk diminishes. None of these steps requires re-pricing the store; they change only how a cashier makes change for a narrow set of transactions.
The cost case versus the consumer-impact case
On the government side of the ledger, the case is clear: FY2024’s pennies cost more than they were worth, generating an estimated $85.3 million loss at the Mint’s scale of production. That is the anchor for reform. The counter-argument does not dispute that arithmetic; it warns about private-sector and consumer effects centered on rounding. Here the best evidence constrains the stakes. A Richmond Fed analysis estimated that rounding to the nearest nickel would impose a net consumer cost on the order of $6.06 million per year nationally—a small number against the federal savings but not zero to households that rely on cash.
The distribution of that burden matters more than the headline total. Cash users skew toward the unbanked and lower-income households; if rounding is implemented asymmetrically in practice—rounding cash up more often than down, or offering card users exact totals while nudging cash users to pay more—the policy could become mildly regressive at the margin. That is a design and compliance problem, not an iron law of rounding. Symmetric, transaction-total rounding, clearly communicated and uniformly applied, is how other countries kept average effects close to neutral, and it is what U.S. policy drafters are attempting to codify.
Where the real uncertainties lie
Two knowledge gaps are worth separating from rhetoric. First, the public record is strongest on the Mint’s loss and the legislative mechanics; it is thinner on quantified, sector-level transition costs for retailers, banks, and cash-handling logistics. Those are real costs—software updates, training, changes to coin inventory—and they arrive up front rather than as an enduring liability. Second, rounding’s realized effect depends on execution fidelity. If merchants adhere to symmetric rules at the total and register systems implement them cleanly, the Richmond Fed’s small net effect is a reasonable baseline; if practice drifts—rounding per item, rounding up only, or steering cash users into worse outcomes—the burden could concentrate on exactly the households reformers want to protect.
Policymakers can mitigate these uncertainties. Federal guidance can specify symmetric rounding, require consumer-facing disclosures at the point of sale, and encourage state weights-and-measures authorities to adopt uniform enforcement standards. Treasury and the GAO can monitor outcomes with transaction-level audits, publishing data on realized rounding patterns across merchant types and payment modes.
https://twitter.com/FirstLadyMbmny/status/2099662965653778794
Historical and international precedent
The U.S. has been here before. The half-cent was retired in 1857 when its value fell below practical use. Peer economies removed their lowest denominations as inflation eroded utility; the common template kept legal-tender status for existing coins, preserved exact electronic settlement, and limited rounding to cash totals. The through-line is pragmatic: align coinage with real purchasing power and payment habits while protecting consumers through rule design and enforcement. In that light, suspending new penny minting is not radical; it is routine monetary housekeeping.
What this means for consumers and businesses
For most consumers, nothing changes in daily life: prices are still posted to the cent, your card or phone still pays to the cent, and existing pennies in your jar still spend. For cash users, the checkout experience simplifies slightly—fewer coins, occasional rounding up or down according to a posted rule—with the average effect near zero when the rule is symmetric and applied to the final total. For retailers, the payoff is leaner cash handling: lighter coin orders, faster drawer counts, fewer jams in coin dispensers, and marginally quicker lines—benefits that compound at scale even if they are invisible to any single shopper.
Judgment
The evidentiary balance favors suspending penny production. The government’s quantifiable loss from making new cents is large and ongoing; the consumer rounding risk, while real for cash users, is measurable, manageable, and principally a matter of implementation quality rather than of principle. The responsible path is not to mint loss-making coins indefinitely; it is to end production, codify symmetric cash-rounding at the transaction total, and monitor practice to keep outcomes fair. That is how you retire a habit without taxing the people who can least afford it.
Sources:
facebook.com, nbcphiladelphia.com, coinnews.net, bakerinstitute.org, congress.gov, en.wikipedia.org, washingtontimes.com