Gas prices at the pump are not a single story about presidential willpower; they are the visible edge of a global system in which crude supply shocks, refinery bottlenecks, and market structure move in concert—sometimes brutally so for households and lucratively so for producers.
The Short Version
- Crude oil costs are the dominant driver of retail gasoline prices; geopolitical disruptions can raise pump prices quickly, while resolution can ease them—often unevenly and on a lag.
- President Trump framed recent price spikes as a temporary, war-driven phenomenon and forecast a sharp decline once the conflict abates, while pointing to very large oil-and-gas revenues during the run-up.
- Critics focus on outsized refining and corporate profits during tight markets, arguing that company margins amplified consumer pain and warrant policy responses like windfall taxes and anti-gouging rules.
- Both perspectives describe parts of the mechanism; the hard question is pass-through: how crude shocks, refining capacity, and market behavior translate into the price paid by motorists—and how quickly that price falls when the shock ends.
How gasoline prices really form: the mechanism behind the marquee number
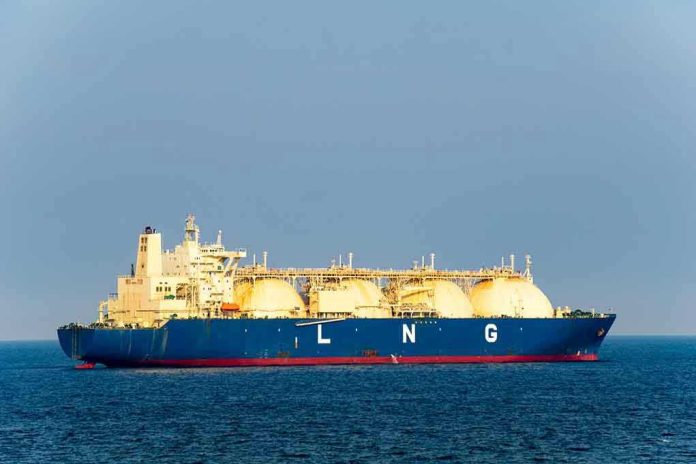
Every time drivers stare at a forecourt sign, they are seeing four components rolled into one: crude oil, refining costs and profits, distribution and marketing, and taxes. Crude is usually the largest slice. When global benchmarks move—because a shipping lane narrows, sanctions bite, or producers curtail output—retail prices tend to follow because refiners pay more for feedstock and pass through those costs, with some delay, to wholesalers and retailers. Taxes are comparatively stable; distribution and marketing swing less than crude or refining margins. In short, when geopolitics crimps supply, crude leads the parade, and the pump follows, albeit with timing quirks that reflect inventories, contract terms, and local competition.
Refining is the crucial middle gear. Even with abundant crude, if complex refineries are offline for maintenance or damaged, or if capacity is tight relative to seasonal demand and fuel specifications, the “crack spread” (the margin between product prices and crude) can widen dramatically. That is not theory; industry data and analyst commentary have shown periods when diesel and gasoline margins surged during disruptions, magnifying the hit to consumers beyond crude alone.
Trump’s claim in context: a supply shock framing with a testable forecast
At a Georgia rally, President Trump cast elevated oil prices as a temporary consequence of war-linked supply risk—specifically, shipping through the Strait of Hormuz—and predicted that prices would “fall dramatically” once the conflict ends. He coupled that diagnosis with an observation that U.S. oil-and-gas producers were earning unusually large sums in the meantime, describing the country as “making a fortune.” The political optics of the phrasing drew heat, but the causal frame—geopolitics raises crude; crude lifts pump prices; post-conflict normalization relieves them—tracks the market’s usual transmission channels.
That forecast is empirically checkable. If the relevant hostilities de-escalate and shipping, insurance, and flows normalize, crude benchmarks should soften, narrowing refining margins unless capacity remains constrained; retail prices would then drift lower with inventory turnover. The timetable is inherently imprecise because product stocks, refinery outages, and seasonal demand can delay or dampen any relief. But the direction of travel—shock up, resolution down—accords with decades of price behavior during and after supply disruptions.
Where the real disagreement lies: margins, profits, and pass-through
The sharpest critique of Trump’s posture does not contest that wars move oil; it argues that oil and refining companies captured more than their share of the upside while households bore the cost. Senator Richard Blumenthal and others point to years in which majors booked very large profits amid high gasoline prices and propose windfall taxes and anti-price-gouging rules as remedies. Independent analyses have highlighted episodes of elevated refining margins—particularly in diesel—suggesting that product scarcity and capacity limits amplified crude-driven price increases.
Two cautions keep this argument honest. First, high profits during tight markets do not, on their own, prove anti-competitive conduct; they are consistent with scarcity pricing in capital-intensive industries where capacity additions take years. Second, conflating producer revenue with national welfare is sloppy accounting: stronger upstream and refining cash flows can coexist with regressive household burdens at the pump. Both truths can be—and often are—simultaneously valid. The policy question is whether observed margins reflect efficient scarcity signals or market power and coordination that merit intervention; that determination rests on granular evidence of costs, capacity, inventories, and competitive behavior, not on headlines.
Timing matters: why prices rise fast and fall slowly
Consumers rightly notice that retail prices often jump quickly when crude spikes but recede more slowly when crude eases. Several features explain the asymmetry. Retailers sell down higher-cost inventory before cutting posted prices; wholesalers adjust rack prices with reference to near-term product futures and spot markets, not today’s crude alone; and local station competition varies block by block. On the way up, futures and spot products reprice immediately, and stations follow to avoid selling at a loss; on the way down, the system clears more gradually. The result is plausible “rockets and feathers” dynamics that fuel frustration and, at times, regulatory scrutiny.
Refinery capacity is the other structural timer. Building or materially expanding a U.S. refinery is a multi-year endeavor entailing billions in capital, environmental permitting, and uncertain long-run demand for hydrocarbons as vehicle efficiency and electrification advance. Analysts repeatedly emphasize that these constraints limit how fast added supply can discipline margins, which is why appeals to instant price relief through new capacity are more political rhetoric than operational plan.
Adjudicating the competing claims: what the strongest evidence supports
On the central question—whether a war-driven supply shock largely explains a period of high pump prices—the weight of energy-market mechanics and historical experience supports the claim. Crude oil’s share of the gasoline price stack means that geopolitics which tightens crude supply usually transmits into retail prices; when the conflict abates and flows normalize, prices typically ease with a lag, conditioned by refining and inventory dynamics. On the distributional question—who benefits and who pays—the record of high profits at producers and refiners during tight markets is well documented, including instances of unusually wide refining margins. That demonstrates strong earnings in a constrained system; it does not, by itself, allocate culpability for the entirety of the price increase between input costs and corporate conduct.
Finally, point estimates tossed around in rallies—“hundreds of billions,” even “trillions”—are rhetorically vivid but economically ambiguous without a defined basis: gross revenue, net profit, tax receipts, royalty flows, export values, or national income. An audit-quality decomposition requires SEC filings, BEA national accounts, federal and state tax data, and export records aligned to the shock window. In energy economics, definitions do the heavy lifting.
Trump on high gas prices: 'We're making a freaking fortune' Trump said on Saturday that American oil companies are making a "fortune" on the Iran war.
•Americans, however, are paying record prices at the pump, according to AAAhttps://t.co/7cFSATaphZ— JB (@LurkingEye) October 25, 2026
What to watch next: the practical signals of relief—or persistence
For readers tracking whether prices will in fact “fall dramatically,” watch the sequence, not the sound bites. First, crude benchmarks relative to pre-shock levels and shipping insurance through choke points like the Strait of Hormuz. Second, product cracks—especially diesel and gasoline spreads—which reveal whether refining is easing or still binding. Third, refinery utilization and unplanned outages heading into seasonal demand peaks. Finally, retail margins and regional rack prices, which show how quickly wholesale relief is filtering to the forecourt. If conflict resolution is real and capacity healthy, the chain will ease in that order; if any link stays tight, relief at the pump will be partial and slow.
Sources:
youtube.com, newsweek.com, commondreams.org, rawstory.com, thedailybeast.com, thehill.com, ftw.usatoday.com, blumenthal.senate.gov